Instalments: consumers can buy now and pay later
Instalments: consumers can buy now and pay later
Visa has developed instalment solutions
Visa has developed instalment solutions
*Availability is subject to factors outside of Visa’s control, including participation by issuers, acquirers and merchants.
Introduction to instalment payments
Introduction to instalment payments
The following example shows how instalment payments work for a large-ticket purchase of $800 paid for over 4 months, 0% fees:
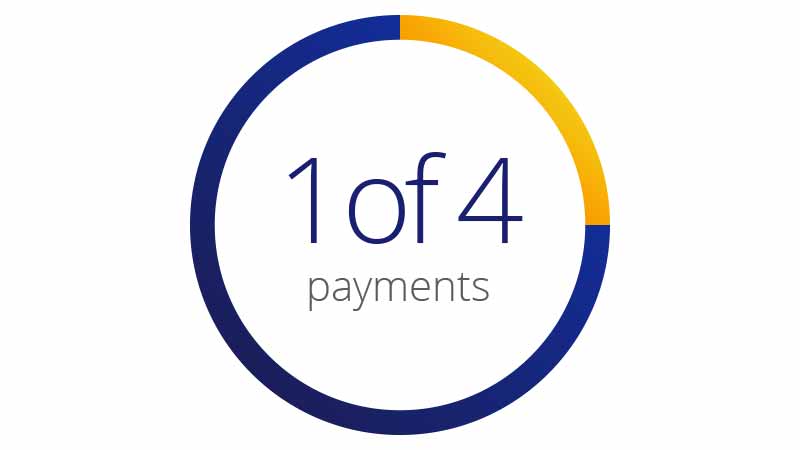
Paid $200
First instalment
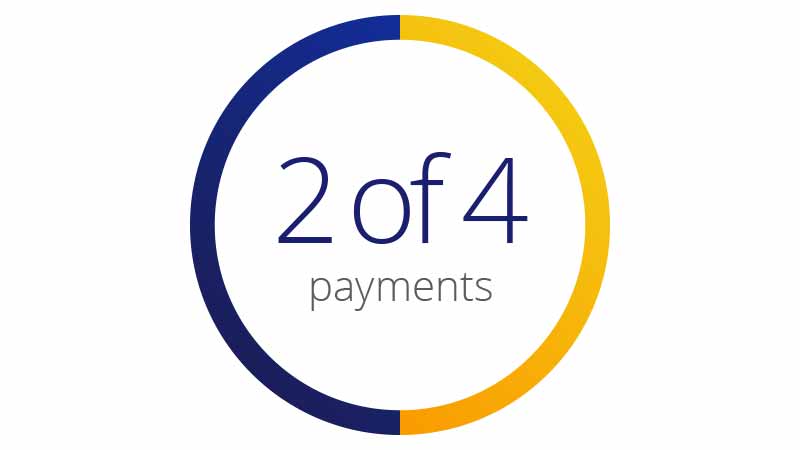
Paid $200
Second instalment
Paid $200
Third instalment
Paid $200
Fourth instalment
Common instalment payments models
Common instalment payments models
*Financial institutions are solely responsible for their own instalments programmes.
During purchase
Consumer prompted at merchant check out to pay in instalments
Post-purchase
Consumer converts a recent card transaction into instalments
Visa’s instalment solution can provide benefits to all parties in the ecosystem
Visa’s instalment solution can provide benefits to all parties in the ecosystem
Note: depicts conceptual vision in development; features, functionality and availability are subject to change. Issuer is solely responsible for its own instalments programme.
Instalments are a large and growing opportunity
Instalments are a large and growing opportunity
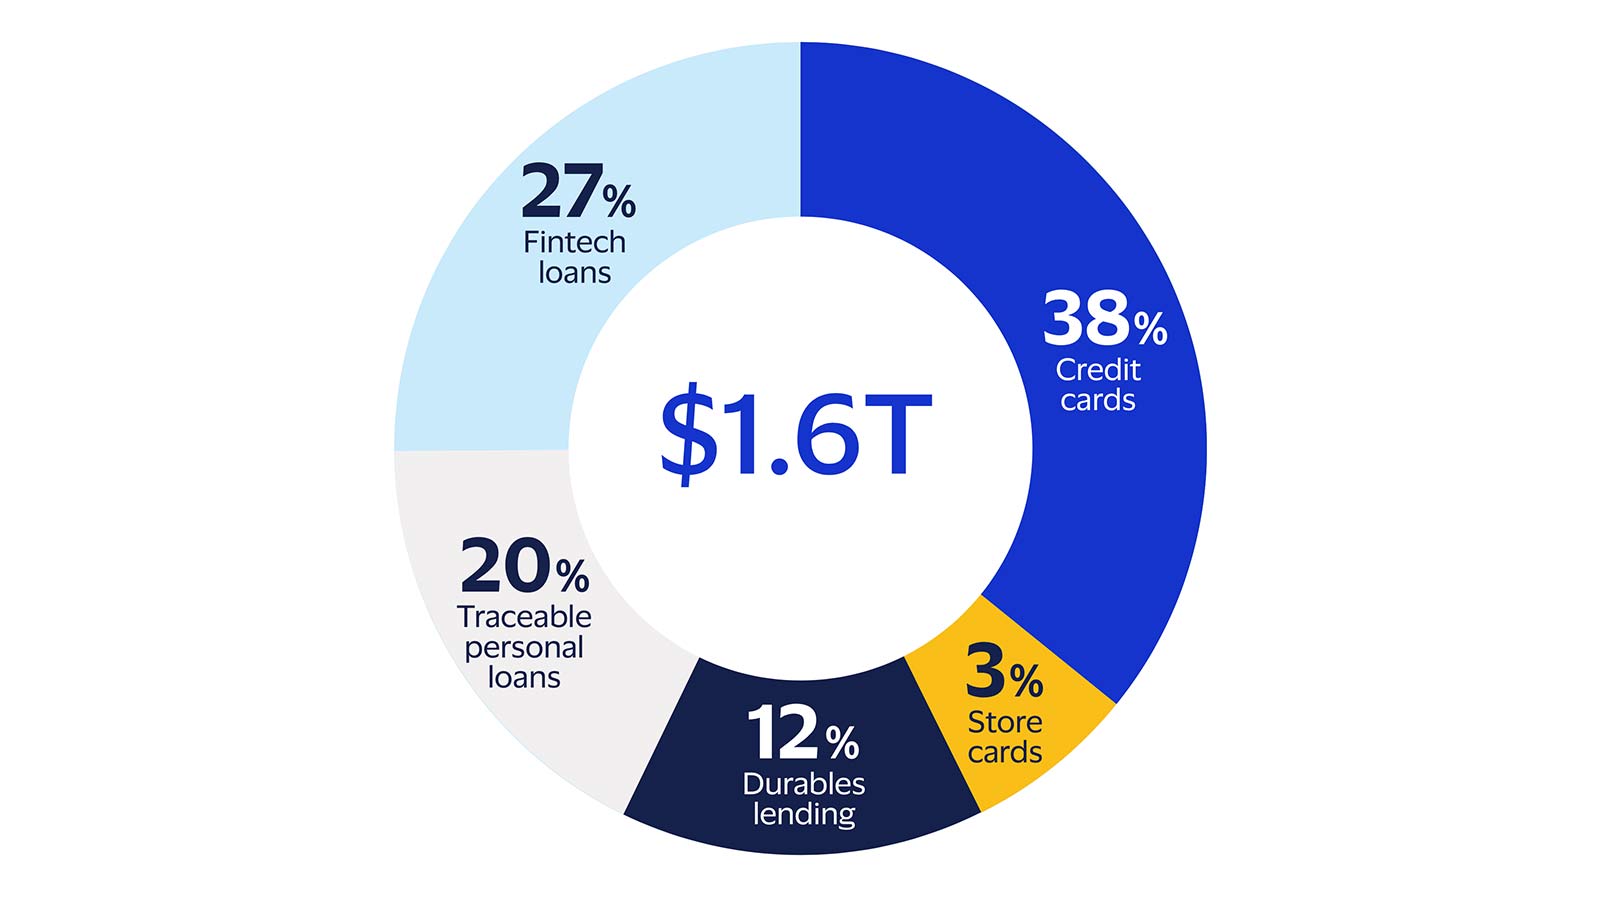
Global instalments market size
Note: 2020 global instalments market size ($1.6 trillion) excludes $1.02 trillion in untraceable instalments volume (e.g., “debt consolidation”). Growth in global instalments and credit cards shown as year-over-year increase in payments volume in 2019 vs 2018.
Source: Visa-commissioned study performed by Euromonitor September 2021